for nonprofits
How the Section 170(e)(3) Tax Deduction Works for Donated Inventory
The enhanced deduction that makes donating unsold inventory cheaper for a company than trashing it, explained for the nonprofit asking.
Panos Kokmotos |
How the Section 170(e)(3) Tax Deduction Works for Donated Inventory
A C corporation that donates unsold inventory to a nonprofit can deduct more than what the goods cost to make. Under Internal Revenue Code Section 170(e)(3), the company can write off its cost basis plus half the markup between cost and fair market value, capped at twice the basis. For a company sitting on inventory it would otherwise write down or landfill, that math often beats a straight liquidation sale. Knowing this rule, and being able to explain it in one paragraph, is the difference between a corporate donor who shrugs and one who says yes.
Who actually qualifies for the enhanced deduction
The enhanced deduction under 170(e)(3) is written for C corporations. An S corp, a partnership, or a sole proprietor donating inventory can still deduct it, but only at cost basis, not the enhanced amount. This matters when you're pitching a donation: if the company you're talking to is a large C corp with a retail, consumer goods, or manufacturing operation, the enhanced deduction is real leverage. If it's a small S-corp-structured local business, the pitch has to rest on the relationship and the goodwill, not the extra tax math.
There's one broad exception. Donations of qualifying food inventory get enhanced-deduction treatment regardless of entity type, a rule Congress made permanent in 2015. So a grocery distributor, food manufacturer, or restaurant group structured as an LLC or S corp still gets the enhanced calculation for food specifically, even though it wouldn't for donated furniture or electronics.
How the deduction is calculated
The formula: cost basis, plus half of (fair market value minus cost basis), not to exceed two times the cost basis. In plain terms, a company that manufactured a product for $10 and would normally sell it for $30 gets to deduct $20 (the $10 basis plus half the $20 markup), well above what it paid, and well below what it would have earned selling it. That's the incentive: the tax benefit narrows the gap between donating and selling closely enough that donating becomes the easier, lower-hassle choice, especially for inventory that's slow-moving, discontinued, or approaching an expiration or season change.
What makes it a "qualified contribution"
The IRS doesn't hand over the enhanced deduction for any inventory gift. To qualify:
- The donee must be a 501(c)(3) organization.
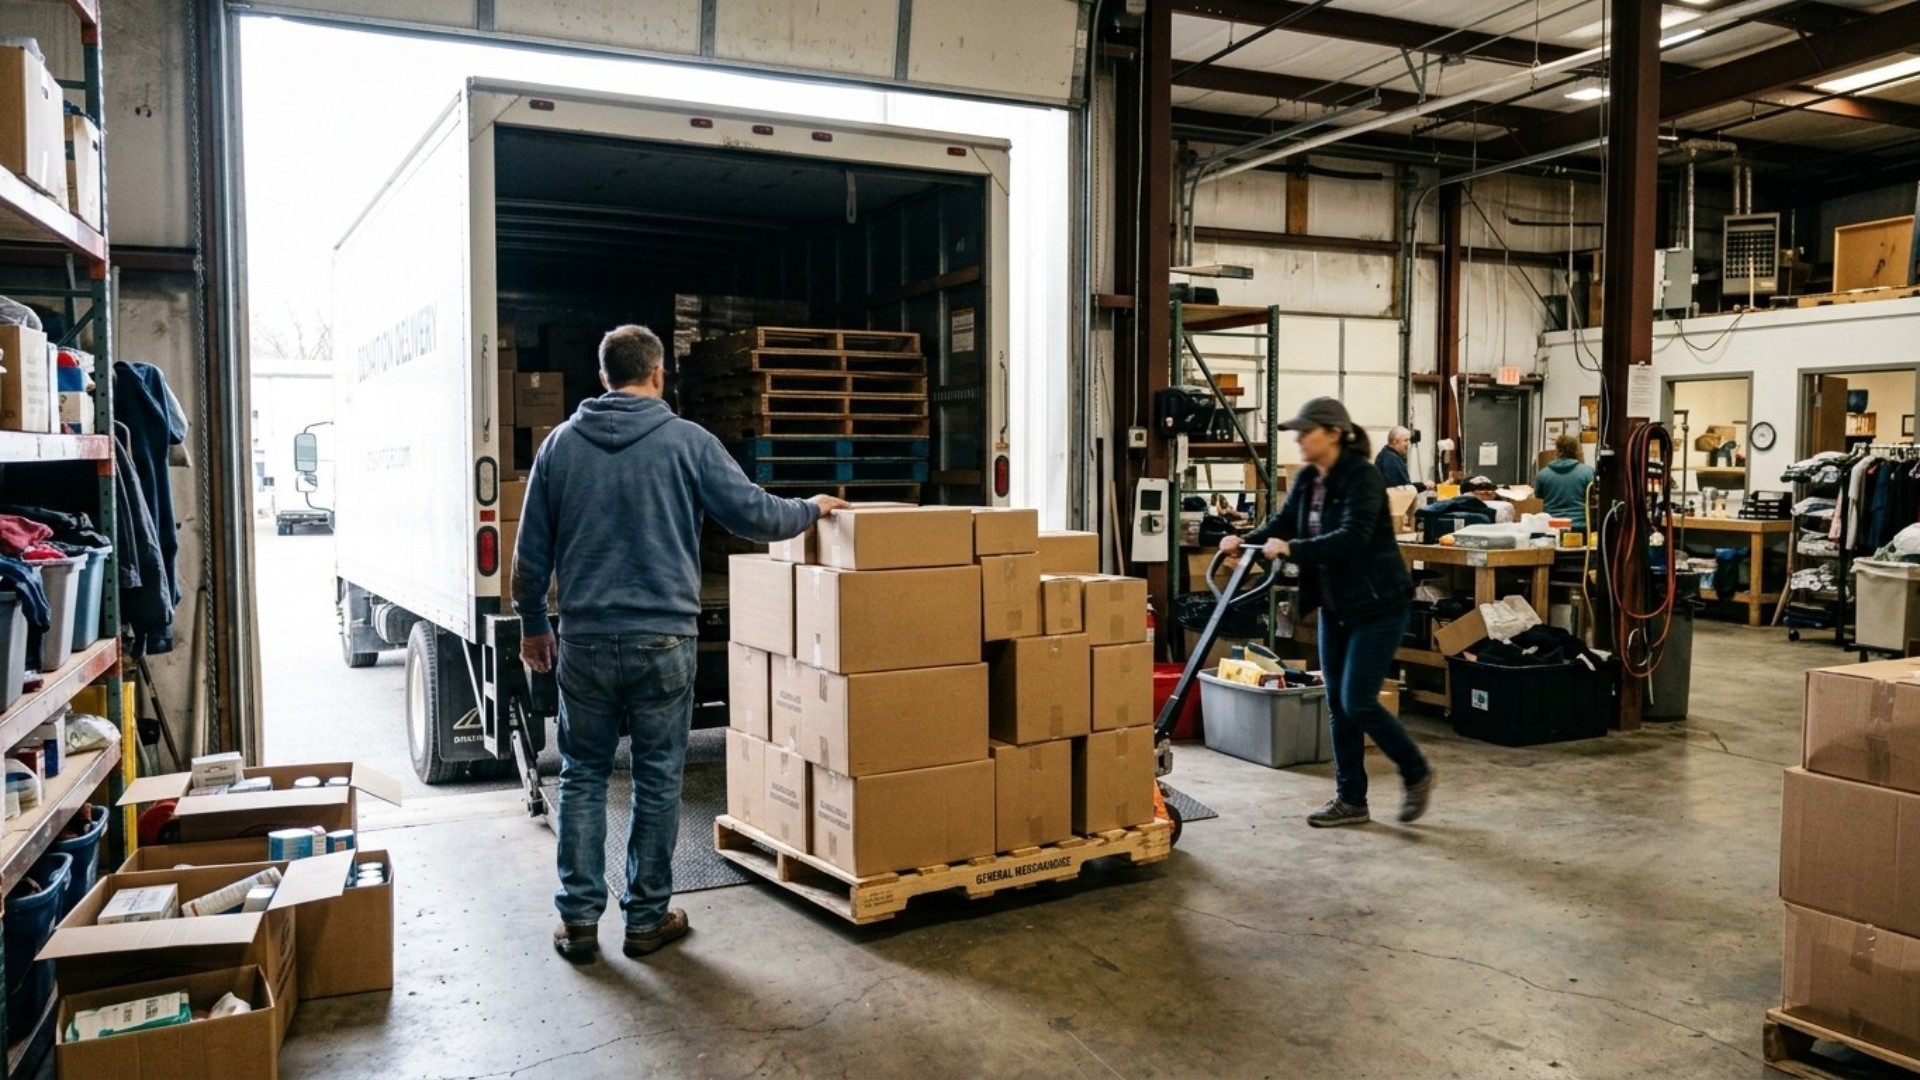
- The donated property has to be used by the nonprofit consistent with its exempt purpose, specifically for the care of the ill, the needy, or infants. A homeless shelter distributing donated clothing and hygiene products fits cleanly. A nonprofit that turns around and sells the inventory does not.
- The nonprofit can't transfer the property for money, other property, or services.
- The company needs a written statement from the nonprofit describing how the property will be used, confirming it meets the "ill, needy, or infants" standard, and confirming it won't be sold or exchanged.
- The company has to keep records supporting fair market value and document what the nonprofit received and when. That last point is where nonprofits can make themselves genuinely useful to a corporate donor: showing up ready to provide a clean, dated acknowledgment letter that matches what the company's tax preparer needs removes friction the company would otherwise have to chase down itself.
Why this belongs in your pitch to a company, not just your accountant's toolkit
Most nonprofits treat inventory donations as a favor they're asking for. Framed around 170(e)(3), it's closer to a trade: the company avoids disposal costs, gets a real tax benefit larger than its basis, and offloads inventory that's taking up warehouse space, in exchange for a documented gift and a photo of where it landed. That reframe changes the conversation with a corporate donor from "please help us" to "here's what this actually costs you, and it's less than you think."
FAQ
Does 170(e)(3) apply to used equipment or only new inventory? It applies to inventory, meaning property held for sale in the ordinary course of business, not used equipment a company owns and depreciates. A retailer's unsold stock qualifies. A company's used office furniture doesn't get this specific enhanced treatment, though it can still be deducted at fair market value under general charitable-contribution rules.
Can a small business without C-corp status get any deduction for donating goods? Yes. Any business entity can deduct the donation at cost basis under standard charitable contribution rules. It just doesn't get the extra markup deduction that C corps and, for food specifically, all entity types can claim under 170(e)(3).
What if the nonprofit isn't sure whether the donated goods fit "care of the ill, needy, or infants"? That standard is interpreted broadly to include most direct-aid distribution: food, clothing, hygiene products, baby items, medical supplies, and household goods given to people in need. It doesn't cover inventory the nonprofit resells for revenue, which is a separate question with its own tax rules for the nonprofit's side.
Does the nonprofit need to issue a specific kind of receipt? Yes. The acknowledgment needs to describe the donated property, state that no goods or services were exchanged for it, and confirm how the nonprofit will use it. It should not state a dollar value; valuation is the donor's responsibility, not the nonprofit's.
What to do with this
If your organization runs a wishlist of specific, current needs, that list is exactly what makes this pitch land: a company can see precisely what would qualify, and can match its own unsold inventory to a documented, exempt-purpose use before it ever asks. Browse how nonprofits list their real needs on Givelink and see what a documented ask looks like before your next conversation with a corporate donor.
See also
What is Givelink?
Learn from the founders:
Run a nonprofit? Get what you need.
Set your nonprofit up yourself in about 15 minutes. It's free, there's no contract, and you don't need to talk to anyone first.