for nonprofits
Does the New 2026 Charitable Deduction Cover In-Kind Gifts?
No. The new $1,000/$2,000 deduction for non-itemizers applies to cash only. Here's what that means for donors who give goods.
Panos Kokmotos |
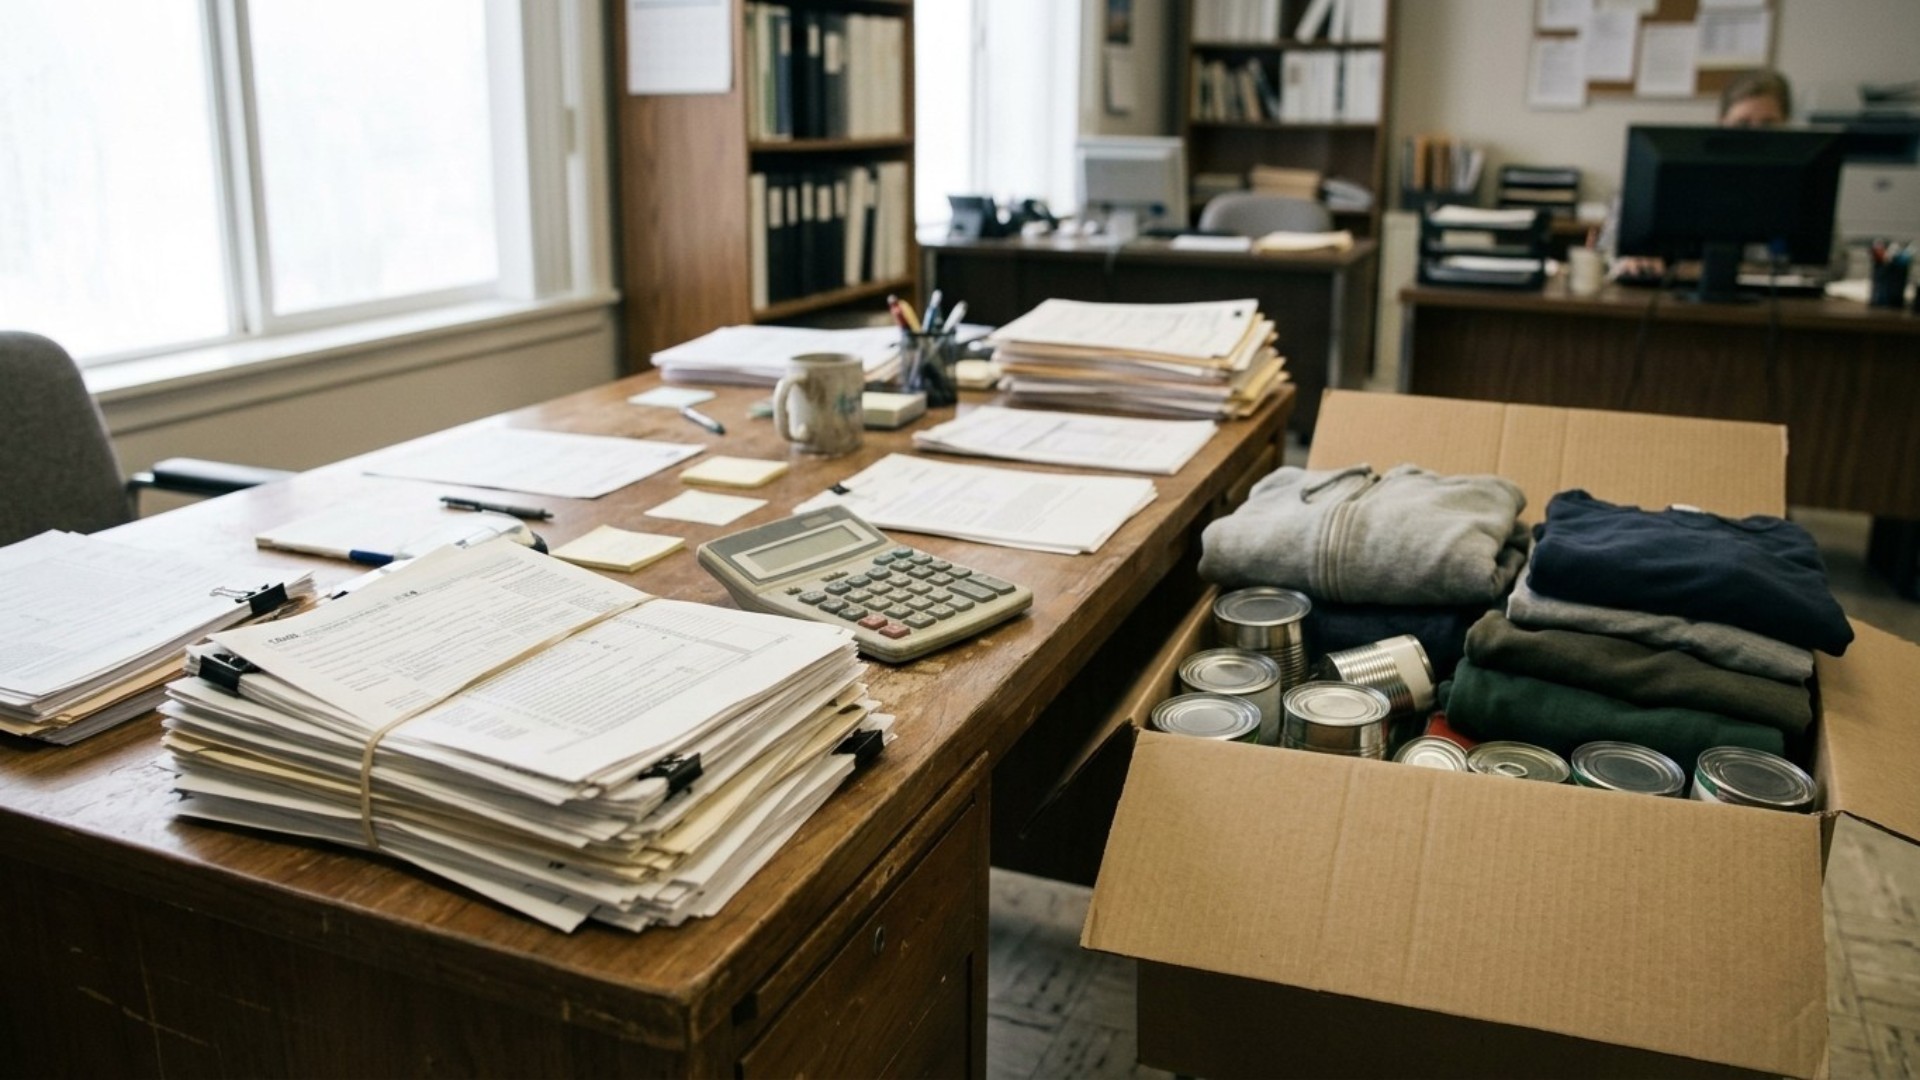
No, it doesn't. The new above-the-line charitable deduction for 2026 applies to cash, check, or credit card gifts only. A donor who gives clothing, food, furniture, or any other physical item can't use this specific deduction for that gift. It's a narrower benefit than a lot of donors assume, and nonprofits that field year-end tax questions should know exactly where the line falls before a donor asks.
What the deduction actually covers
Starting with the 2026 tax year, a taxpayer who doesn't itemize can deduct up to $1,000 (single filers) or $2,000 (married filing jointly) in cash contributions to a qualifying 501(c)(3) public charity, taken directly off taxable income. The dollar caps are fixed amounts, not inflation-adjusted, at least for now. There's no income floor to clear first, which is the real difference from itemized giving: a non-itemizer doesn't need to exceed any percentage of adjusted gross income to claim it.
Three things disqualify a gift from this specific deduction:
- It isn't cash. Property, goods, stock, and services are excluded. The rule text specifically limits it to cash, check, or credit/debit card gifts.
- It goes to the wrong kind of recipient. Gifts to donor-advised funds, supporting organizations, and private foundations don't qualify, even if the underlying cause is legitimate.
- It's undocumented. Any cash gift of $250 or more still needs the usual written acknowledgment from the charity to be claimed.
Why in-kind gifts were left out
The new deduction was built to give non-itemizers a simple, low-friction benefit for cash giving, the kind of gift that's easiest to verify and easiest for the IRS to audit against a bank or card statement. Valuing donated goods is messier: a used couch, a case of diapers, or a box of children's books doesn't have one obvious dollar value the way a $50 charge does. Keeping the new deduction cash-only avoids opening that valuation question for a benefit meant to be simple.
That doesn't mean in-kind gifts lost their tax treatment entirely. It means they're still governed by the older, separate rules for itemized non-cash contributions, which haven't gone away.
What this means for a donor who gives goods
A donor who only ever gives goods and takes the standard deduction gets nothing new here. To deduct an in-kind gift at all, that donor still has to itemize, which means their total itemized deductions (state and local taxes, mortgage interest, medical expenses above the threshold, and charitable gifts combined) need to exceed the standard deduction for their filing status. For most middle-income households, that math doesn't work, and it didn't work before this change either. The new deduction doesn't open a door for them; it just doesn't apply.
For a donor who itemizes and also gives goods, nothing changes. The existing rules still apply: a deduction based on fair market value for most items, a qualified appraisal required above $5,000, and Form 8283 attached to the return for any single non-cash gift over $500.
What your nonprofit should tell donors this year
Be precise when a donor asks whether their donated goods qualify for "the new deduction." The honest answer is that the new deduction won't apply, but the gift may still be deductible under the older rules if they itemize. Conflating the two invites a bad surprise at filing time and a donor who feels misled by the organization that told them otherwise.
If a donor gives both cash and goods in the same year, they can potentially use the new $1,000/$2,000 deduction for the cash portion even while taking the standard deduction overall, and separately itemize the in-kind portion only if itemizing makes sense for their full return. Those are two independent decisions, not one combined deduction.
None of this changes anything about how a nonprofit should collect and acknowledge in-kind gifts operationally. A clear, itemized thank-you letter describing what was donated (without assigning it a dollar value, which is the donor's job, not the charity's) still matters regardless of which deduction path a donor ends up using. See how to write an in-kind donation thank-you letter for the specifics on what belongs in that acknowledgment.
For nonprofits still working through the rest of what changed in the 2026 tax rules beyond this one deduction, this year's broader charitable deduction changes cover the full picture.
Where Givelink fits
None of this changes what a nonprofit actually needs: real items, delivered, verified. Givelink lets an organization list the exact goods it needs and lets a donor fund that specific item, with a photo confirming it arrived. It doesn't change anyone's tax treatment, but it does make the in-kind side of giving easier to run and easier to thank someone for correctly. Start a profile at Givelink for nonprofits.
FAQ
Can a donor combine the new cash deduction with an itemized deduction for goods in the same tax year? Only if they itemize for the rest of their return. The $1,000/$2,000 cash deduction is for non-itemizers claiming the standard deduction. A donor who itemizes uses the older non-cash rules for goods instead, not this new benefit.
Does this deduction apply to gifts of stock or cryptocurrency? No. It's limited to cash, check, or credit/debit card gifts. Stock, crypto, and other property follow the existing non-cash contribution rules regardless of whether the donor itemizes.
Do we need to change our donation receipts because of this? Not for in-kind gifts. Keep describing exactly what was donated without assigning a dollar value. For cash gifts of $250 or more, the usual written acknowledgment requirement is unchanged and still applies regardless of which deduction the donor ultimately claims.
Is this deduction permanent or does it expire? The dollar caps are fixed for 2026 without an inflation adjustment for now. Nonprofits should watch for guidance on whether or how the amounts change in future tax years rather than assuming this year's numbers carry forward automatically.
See also
What is Givelink?
Learn from the founders:
Run a nonprofit? Get what you need.
Set your nonprofit up yourself in about 15 minutes. It's free, there's no contract, and you don't need to talk to anyone first.